

Time:2026-11-18 Preview:1
In 2026, the growth logic of China’s precision mechanical components industry is shifting. The development path driven by steady expansion of the general equipment market over the past few years is being reshaped by concentrated capacity expansion in new-energy equipment and semiconductor production lines. Industry demand is no longer evenly distributed incremental growth; instead, it shows obvious structural divergence.
In terms of market size, the segmented market of precision mechanical components in China registered a compound annual growth rate of 9.3% in 2024, with an overall market size of approximately 187 billion yuan. It is projected to exceed 220 billion yuan in 2026. Behind the overall growth, however, the weight of demand across different downstream sectors has shifted noticeably: order growth for conventional machine tools and traditional automobile manufacturing is slowing, while demand for precision supporting components used in new-energy battery production lines, photovoltaic equipment and semiconductor wafer manufacturing equipment is growing far above the industry average.
Changes on the demand side are first reflected in substantially higher precision requirements. Photovoltaic tin-plated copper strip production lines and lithium battery electrode coating equipment within new-energy hardware, as well as core structural parts for semiconductor packaging, generally require dimensional stability at the ±0.005 mm level. The surface roughness of some key mating surfaces must be controlled within Ra ≤ 0.2 μm. Such orders are no longer satisfied with standard “qualified machining”; instead, components must maintain stable geometric tolerances throughout their lifecycle to prevent minor deformation from undermining the operational accuracy of the entire production line.
The procurement logic of downstream customers is also shifting. Leading new-energy equipment and semiconductor equipment manufacturers no longer source scattered machined parts separately as they once did. They prefer suppliers capable of delivering turnkey precision manufacturing services. Full supporting capabilities are required, covering early-stage process simulation and material matching for structural parts, full-process data traceability during machining, and subsequent verification of batch stability. Mid-sized equipment integrators place greater emphasis on flexible delivery capacity. Faced with low-volume, multi-variety non-standard custom orders, the ability to quickly complete sampling and deliver small-to-medium batches has become a core threshold for winning contracts.
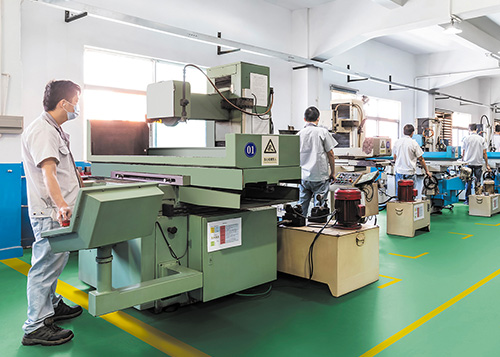
Upstream precision mechanical component suppliers along the industrial chain are also adjusting their capability layout in response to shifting demand. Many factories previously relied on general CNC equipment for mass production. Now they are selectively introducing five-axis machining centers and ultra-high-precision wire EDM equipment, and building closed-loop inspection systems to meet the special machining requirements of emerging sectors. Some niche-focused enterprises have achieved stable mass delivery for applications such as wind turbine gearbox housings, semiconductor pump and valve brackets, and precision filtration assemblies for water treatment. They have built differentiated competitive advantages through deep process expertise.
It is worth noting that the ongoing structural shift in the precision mechanical components industry is not a short-term market fluctuation, but an inevitable phase amid the domestic substitution of high-end equipment. Continuous capacity expansion in the two high-growth tracks of new energy and semiconductors is pushing upstream suppliers to move away from low-value price competition and upgrade toward high-precision, customised manufacturing. Enterprises that can reliably meet the needs of these two sectors, maintain consistent tolerances and deliver uniform batches will secure a more favourable market position amid this industrial restructuring.
Source: Baidu

 Free Service Hotline:
Sales Hotline:
 Email:allisonho@foxmail.com
 Address:1st Floor, Building E, No. 6, Hongye South 2nd Road, Tangxia Town, Dongguan City, Guangdong Province
 Fax:0769-82865290